If your business insurance renews in June, you may already know it can be a busy time for the insurance industry.
Many businesses choose June renewals because they align with the end of the financial year. However, this also means insurers are reviewing a high number of policies at the same time.
Moving your renewal away from this busy period may have some benefits, including:
1. More time for Insurers to assess your business
A quieter renewal period may give insurers more time to understand your business, assess your risks and consider the terms they can offer.
This can be especially helpful if your business has changed, your risks are more complex or your policy needs a more detailed review.
2. More opportunity for us to negotiate
Having more time can also give us greater opportunity to speak with underwriters, explore alternative markets and negotiate premiums and policy conditions on your behalf.
It allows us to thoroughly consider the options available and work with insurers to find the right solution for your business.
You May Be Able to Change Your Renewal Date
Many business owners with a June renewal assume they need to renew in June every year. In some cases, that’s not necessarily the case.
Depending on your insurer and policy, we may be able to arrange a one-off policy term of 8 to 16 months.
This could move your next renewal to a different time of year.
For example, if your policy currently renews in June, we may be able to extend the policy term so your next renewal falls later in the year, outside the industry’s peak renewal period.
Is It Worth Asking?
Changing your renewal date won’t suit every business.
We’ll look at your circumstances, see whether it’s an option and explain what may work best for you.
Planning ahead could give insurers more time to assess your business and give us more opportunity to negotiate the right cover and terms on your behalf.
We know when something goes wrong, making an insurance claim can feel like one extra hassle.
As a business owner we also know your priority is usually getting things back to normal or continuing to run with as little disruption as possible.
However, what you do after an incident can affect how smoothly your claim is handled.
As your insurance advisor, we are here to help guide you through the claims process. Here are five of the most common mistakes that can make a claim more difficult.
1. Waiting too long to notify us
One of the most common mistakes we see is waiting too long to report an incident.
You may think the damage is minor or you want to look into all details of what happened before contacting us.
However, it is best to let us know as soon as possible.
Early notification gives us the chance to understand what has happened and help you take the right steps.
Your policy may also have rules about when and how you need to report a claim.
Our advice: If something happens that could lead to a claim, contact us as soon as possible. Even if you are unsure whether you want to make a claim, we can help you understand your options.
2. Not keeping evidence
Good records can make a big difference during a claim.
Where it is safe to do so, take photos and videos of the damage. Keep receipts, invoices, repair quotes and other records linked to the incident.
It is also useful to keep emails and other messages about the incident. This may include conversations with contractors, suppliers or other people involved.
The more information we have, the easier it can be to understand what happened and assess the loss.
Our advice: Keep records of the incident, the damage and any costs. Don’t rely on memory alone.
3. Starting repairs too soon
We understand that when your business is damaged, you want to fix the problem straight away.
In some cases, urgent action is needed to make the area safe or stop the damage from getting worse.
However, starting non-urgent repairs before speaking with us may make it harder to assess the damage. The insurer may need to inspect the property or arrange an assessment before repairs begin.
Our advice: Contact us before starting non-urgent repairs. If urgent work is needed, take photos first where it is safe to do so and keep records of the work and costs.
4. Assuming something is covered
It is easy to think that if you have insurance, your loss must be covered.
But insurance policies can be complex. They can include different terms, conditions, exclusions, limits and excesses.
Cover can also depend on what happened and how the loss occurred.
Rather than making assumptions, talk to us about your policy and the situation. We can help explain what your cover may respond to and what steps you should take next.
Our advice: Don’t guess. If you are unsure whether something is covered, ask us before making decisions.
5. Not understanding your excess
Your excess is the amount you may need to pay towards a claim.
The amount can vary depending on your policy and the type of claim. Some policies may also have different excesses for certain events.
Knowing your excess before you need to make a claim can help you understand the possible cost to your business.
Our advice: Make sure you know what excesses apply to your policies. If you are unsure, we’re happy to explain them.
What should you do if something goes wrong?
EvEvery claim is different, but there are some simple steps you can take.
Make the area safe. Put the safety of your employees, customers and others first.
Prevent further damage. Take reasonable steps to protect your property where it is safe to do so.
Document the incident. Take photos and videos and write down what happened.
Contact us. Let your broker know as soon as possible.
Keep your records. Save invoices, receipts, quotes and other documents.
Importantly we are here to help, ask questions. If you are unsure what to do, speak with us before taking action.
The best time to review your insurance is before a claim
A claim can highlight whether your insurance still matches your business needs.
Your business may have changed since your policy was first arranged. You may have bought new equipment, increased your stock, moved premises, hired more employees or changed how you operate.
That’s why regular insurance reviews are important.
At East West Insurance Brokers, we work with you to understand your business and help you make informed decisions about your insurance.
If your business has changed, speak with your broker. We can review your cover and help make sure it still suits your needs.
Because the best time to find a gap in your insurance is before you need to make a claim.
Most business owners think Business Interruption insurance only covers damage to their own premises.
But when we review a client’s cover, we look at more than their own business.
We also consider the businesses they rely on, such as suppliers, customers and storage providers.
If one of these businesses is affected, it could also disrupt your business and reduce your income.
This is where Contingent Business Interruption cover can help.
How Can Contingent Business Interruption Cover Help?
Your business does not need to be directly damaged to suffer a loss.
If a business you rely on is affected, it could cause delays, lower sales or lost income.
When we review Business Interruption cover with our clients, these are some of the key areas we encourage them to think about.
1.Your Suppliers or Manufacturers
Many businesses rely on suppliers for products, materials or equipment.
But what would happen if one of your key suppliers could no longer deliver?
If their premises are damaged, it could delay your business and affect your income.
For example:
A dressmaker cannot source fabric after a supplier’s warehouse is damaged by fire.
A café cannot receive deliveries after a bakery supplier is damaged by a storm.
A construction company faces delays after a supplier’s factory is damaged by fire.
Depending on your policy, Contingent Business Interruption insurance may help cover the financial impact.
This is something we recommend considering if your business relies heavily on a small number of suppliers.
2. Your Customers
Sometimes, the disruption can come from the other side of your business; your customers.
If a major customer is affected by an insured event, they may not be able to operate as normal. They may reduce or stop buying your products or services.
For example, imagine you supply products to a restaurant that is damaged by a storm and needs to close for repairs.
While the restaurant is closed, they may not be able to purchase from you. If they are a major customer, this could have a real impact on your income.
If your business relies on a small number of key customers, Contingent Business Interruption cover may help protect your income.
3.Third-Party Storage Facilities
We also see businesses storing stock at warehouses or storage facilities they do not own.
If that location is damaged, it could delay orders and affect your ability to trade.
Your policy may provide protection if the storage facility belongs to another business.
However, we also recommend checking that any stock stored at third-party locations is properly insured.
Two Important Things to Know
Contingent Business Interruption cover can provide valuable protection, but there are some important limits to understand.
1. The Damage Must Be Covered
For your claim to be covered, the damage will usually need to be something your Property Damage insurance would cover.
For example, your supplier’s warehouse is damaged by flood, but your Property Damage policy does not include flood cover.
In this situation, your Business Interruption claim may not be covered.
This is why we always encourage our clients to look at their Property Damage and Business Interruption insurance together. The two covers can work closely together when a claim occurs.
2.Your Claim May Be Limited to 20%
Many insurers place limits on claims involving suppliers, customers or storage facilities that are not specifically listed on your policy.
A common limit is 20% of your Business Interruption Sum Insured, although this can vary between insurers and policies.
For example, if your Business Interruption Sum Insured is $500,000, your claim for an unnamed supplier, customer or storage facility may be limited to $100,000.
For a business that relies heavily on one key supplier or customer, that limit may not be enough.
When we review your policy, we can help you understand these limits and whether they provide enough protection for your business.
Is Your Insurance Keeping Up With Your Business?
Your business does not stay the same forever.
You may work with new suppliers, gain bigger customers, hold more stock or change the way you operate.
That is why we recommend reviewing your insurance regularly.
We encourage you to ask yourself:
What would happen if my main supplier stopped operating?
What if my biggest customer could no longer trade?
Could my business continue if my stock was damaged at another location?
How long could I continue operating if a key business partner was affected?
If the answers raise some concerns, it may be time to review your cover.
As your broker, we can help you understand your policy, explain any limits and look at whether your current cover still meets your needs.
A quick conversation with us today could help you identify a gap before you need to make a claim.
Insurers have significantly tightened their underwriting over the past 12 – 18 months, and the level of data required before quoting has increased acrosss the board.
What’s changed?
Insurers are now scrutinising risk information far more closely than they used to. Where a brief overview may have been enough in the past, underwriters today want specifics: detailed claims histories, updated asset values, current risk management practices, workforce numbers, and revenue breakdowns. We are essentially asking for the works.
It’s not about being difficult. It’s about insurers protecting their books in a tougher market.
And here’s the reality: incomplete or vague information leads to higher premiums, coverage restrictions, or declined quotes.
Why we’re asking (again)
We know it can feel repetitive. You provided this information last year, and your business hasn’t changed significantly. Why do we need it all over again?
Because insurers treat every renewal as a fresh underwriting exercise. They’re reassessing your risk profile based on current information, not last year’s data. If we don’t provide comprehensive, accurate details upfront, we lose negotiation power, and potentially you may lose more as a result.
What good information gets you:
Sharper pricing – Underwriters price what they understand. The clearer the picture, the tighter the premium.
Broader coverage – Detailed risk information helps us argue for better terms, higher limits, and fewer exclusions.
Faster turnaround – Complete submissions avoid the back-and-forth that delays quotes and eats into your renewal timeline.
More options – Insurers are more willing to quote and complete when they have confidence in the information.
Our commitment to you
We are not asking for details to tick boxes. We’re asking to secure the best possible outcome for your business. Every data point you provide gives us leverage to negotiate on your behalf, and in this market, that leverage matters.
We also get that you’re busy. If there’s a way we can make the renewal process easier by pre-filling forms, scheduling a quick call instead of lengthy emails, or consolidating requests, please let us know. We’re here to make this work for you, not add to your workload.
What this means for your business
The more detail we have, the harder we can push for competitive terms. It might feel like extra effort now, but it translates directly into better cover and better value when renewal time comes.
As always, if you’ve got questions about what we’re asking for (or why), we’re happy to walk you through it.
Running a business comes with risks. Accidents, property damage, and legal claims can happen at any time, even when you’ve done nothing wrong. That’s why liability insurance is so important.
At its core, liability insurance is triggered when a claim of negligence is made against you or your business. Even if you did nothing wrong, defending yourself in court can be very expensive. Liability insurance for businesses helps cover both the costs of being found negligent and the significant expenses involved in defending a claim.
Liability insurance protects your business if someone says you caused them financial loss, injury, or property damage. It covers both any compensation you might owe and the legal costs of defending yourself.
This coverage is essential because defending a claim, even if you did nothing wrong, can cost tens or hundreds of thousands of dollars. Liability insurance makes sure you don’t have to pay these costs yourself.
What does Liability Insurance cover?
Liability insurance is meant to protect you from:
Claims of negligence – if someone alleges your actions (or failure to act) caused them financial loss, injury, or property damage.
Legal defence costs – including lawyer’s fees, court filing costs, expert witnesses, and settlement negotiations.
Damages or compensation – if you are found liable.
This applies to a wide range of scenarios, from a customer slipping on your premises to damage caused to someone else’s property while on a job site.
What is the trigger? Negligence
The most common trigger for liability claims is an allegation of negligence. Negligence doesn’t mean you intended to cause harm, it could simply mean someone believes you failed to take “reasonable care.”
For example, a cafe owner might be sued if a customer slips on a wet floor and becomes injured. Another scenario could be a tradesperson being sued if their work is alleged to have caused property damage.
How does it protect your business?
You don’t need to lose a case to lose money. Even if you haven’t been negligent, defending yourself in court can be extremely expensive. Lawyers’ fees, expert reports, and court appearances can quickly add up to tens or hundreds of thousands of dollars.
Liability insurance covers these defence costs, so your business can keep running while the case is ongoing. Without it, you might have to pay out of pocket, which could be a financial blow many businesses can’t handle.
Do you need liability insurance? A broker would know
Liability insurance is not just protection for when mistakes happen. It’s protection against the rising costs of legal disputes and claims, even when you’ve done everything right.
Understanding the level of protection you need can be complex, which is why speaking with an experienced broker can make all the difference. And whether you have questions about your current cover, need guidance on policy options, or want to explore a quote, our team is here to help.
Contact our team at he***@******om.au to discuss your options or request a free quote. Let’s work together to secure your business and keep it thriving.
Cyber risk is one of the most common threats for Australian businesses. It can disrupt operations and cause serious losses.
To help businesses, the Australian Government released the Essential Eight. This is a set of eight practical cybersecurity strategies. They are designed to help businesses get back to trading quickly after a cyber incident.
Essential Eight Cybersecurity Strategies
The Essential Eight encourages businesses to:
1.Keep software up to date: Regularly update your operating systems and applications to close security gaps.
2. Control access: Only allow authorised staff to make important system changes. Remove access when staff leave.
3. Use strong passwords and MFA: Strong passwords plus multi-factor authentication (MFA) add an extra layer of protection.
4. Limit risky programs: Block or restrict applications and macros that are commonly used to spread malware.
5. Back up data often: Make frequent, secure backups. Test them to make sure you can restore data quickly.
6.Protect against phishing and unsafe sites: Reduce risk from malicious emails and dangerous websites.
7.Have a simple response plan: Know what steps to take and who to contact if something goes wrong.
8. Educate your staff: .Use monthly updates from the Essential Eight team to keep staff aware of the latest cyber threats.
Why Cyber Risk Management Matters
Insurers now look closely at cyber risk management when deciding coverage, premiums, and claims for Australian businesses. Businesses that follow frameworks like the Essential Eight are better prepared if a claim occurs.
Demonstrating these controls can also help negotiate stronger coverage or lower premiums.
What You Should Do?
If you’re reviewing your insurance or risk management, now is a good time to consider how the Essential Eight cybersecurity strategies could be implemented in your business. Contact your broker to discuss these controls in detail.
Artificial Intelligence in business is now part of everyday operations. It helps with admin tasks, data analysis, and customer service. It can also help write messages and emails. AI is a useful tool for saving time and improving efficiency.
For many businesses, using AI is no longer a choice. It is becoming necessary to stay competitive. But every new tool brings new risks, therefore, it is important to understand these risks before relying on AI.
Understanding AI
A simple way to think about AI is to compare it to your home. A robot vacuum or dishwasher can save you time. But they only work well if the space is set up properly. If there are items on the floor, blocked pipes, or the machine is too full, problems can happen.
AI works in the same way.
The more AI is used in your business, the more important it is to control how it is used. You will need to manage what it can access and who is responsible for it.
Without clear rules and controls, businesses may face challenges. Effective AI risk management can help reduce:
Data privacy and confidentiality breaches
Cyber attacks or system failures
Incorrect results or false information
Intellectual property or copyright problems
Legal or regulatory issues
The Role of Business Insurance for AI
From an insurance point of view, protection must keep up with new technology.
Many insurance policies do not clearly cover AI-related problems. This is common when data, cyber risk, or professional advice is involved. Just as you protect your home and contents, you should also protect your business. This means checking your insurance regularly and making sure your coverage matches how your business uses technology, including AI.
Keeping Business Efficient and Protected
AI can make running your business easier and faster. The key is to set it up properly and ensure you have the right protection in place.
If your business is starting to use new technology or is expanding its use of AI, now is the time to talk to your broker. A review of your risk management and insurance cover, including AI risk management strategies will help make sure your protection grows with your business.
When arranging insurance for a commercial property, many owners make a common mistake: using the purchase price as the sum insured.
On the surface, it feels logical. If that’s what you paid for the property, surely that’s what it’s worth? However, the purchase price doesn’t always reflect the actual cost of rebuilding.
Purchase Price vs. Rebuild Value
It’s important to understand the difference between the purchase price and rebuild value when it comes time to insuring your property. Yes, both relate to what your property is worth, but they represent and serve very different things.
Purchase Price
The purchase price of a property represents the total amount paid to acquire it on the market. It’s affected by several factors, which include:
The value of the land.
The property’s location and market demand.
Broader economic conditions at the time of purchase.
None of these is relevant to an insurer if your building is damaged or destroyed. Insurance is about replacing the structure itself, not the land it sits on.
Rebuild Value
The sum insured is generally expected to reflect the full replacement value of the building, which includes:
Demolition and debris removal.
Professional fees (engineers, architects, surveyors).
Current labour and material costs.
Compliance upgrades (to meet today’s building codes).
What’s the difference?
The key difference between purchase price and rebuild value lies in what each represents. The purchase price reflects the property’s market value, including the land, location, and broader economic factors, while the rebuild value focuses solely on the cost to reconstruct the building if it were damaged or destroyed. This includes demolition, debris removal, professional fees, materials, labour, and any upgrades needed to meet current building codes. In short, insurance covers the cost to rebuild, not the market price you paid.
The cost of getting it wrong
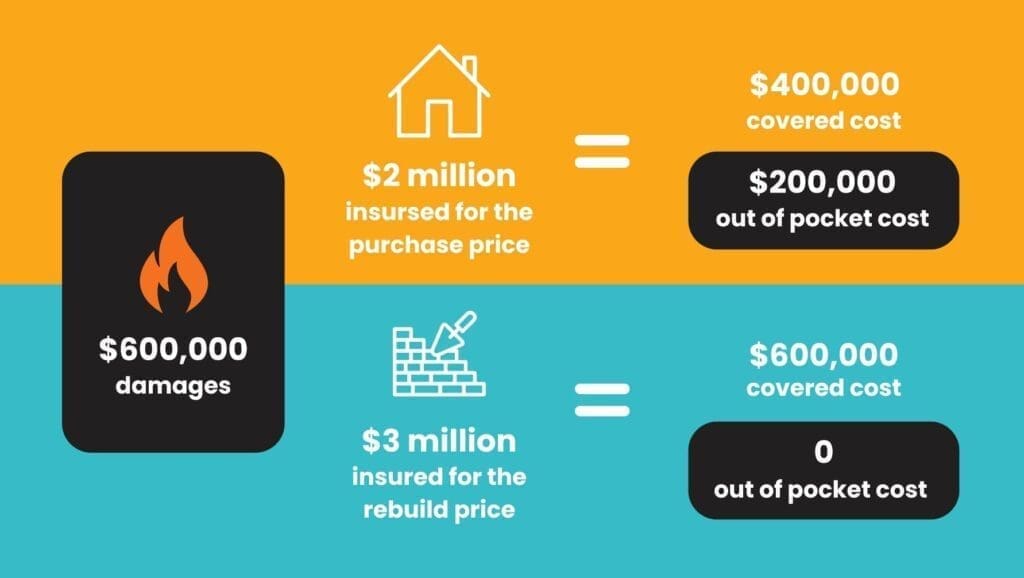
If your sum insured is based on the purchase price rather than a professional valuation, you risk being underinsured. And underinsurance doesn’t just affect you in the event of a total loss. It can also reduce your payout even in the case of a partial claim. For example:
A property was purchased for $2 million, but the actual rebuild cost is $3 million
The sum insured is set at $2 million (instead of $3 million).
A fire causes $600,000 worth of damage
Because the building was underinsured by one-third, the insurer may pay only two-thirds of the claim (about $400,000)
This could leave you, the owner, with $200,000 out of pocket expenses even though the damage wasn’t a total loss.
Why professional property valuations matter
Construction costs in Australia have surged in recent years, driven by shortages of materials and skilled labour. Without a proper valuation, it’s easy to underestimate the cost of rebuilding today compared to when you purchased the property. A professional building valuation gives you:
Confidence that your sums insured are accurate
Protection from co-insurance penalties
Peace of mind that your biggest asset is covered correctly
It’s best to arrange a professional building valuation every few years and review your insurance sums annually. That way, your cover keeps pace with any changes to your property, as well as rising rebuild costs and inflation.
Avoid underinsurance with proper valuation
The purchase price reflects market conditions, not rebuilding costs. Having a commercial property is already a significant investment, and underinsurance can create unexpected financial strain during claims. To safeguard your investment, arrange a professional building valuation and review it regularly. That way, your insurance truly reflects today’s replacement costs, not yesterday’s market value.
When it comes to protecting your assets and ensuring the sums are properly accounted for, a Broker would be a huge help. If you want advice or are interested in learning about available options for commercial property coverage, reach out to East West Insurance Brokers today.
Protect your business with tailored commercial property insurance from our Australian experts. Over 40 years of experience. Get your free quote today!
What do a cozy cafe, a small retail shop, and a towering office building have in common? They all face similar risks when it comes to protecting their property. From fires and floods to theft and vandalism, these unexpected events can disrupt operations—or even force a business to shut down entirely.
That’s why having appropriate commercial property insurance is important. Whether you own or lease your space, your insurance can be the lifeline safeguarding your business from financial fallout.
But before you start insurance shopping, you should first get your commercial property professionally valued.
What is a property valuation?
The estimated market value of a property, which a qualified professional appraiser usually performs. This assessment is based on various factors, which include:
Condition of the property
Existing structures
Location and proximity to other facilities
Market trends
Renovations and upgrades
Size and layout
Valuation of similar properties within the area
There are two main types of property valuations, each serving different purposes. Understanding the distinction between them is crucial to avoid costly mistakes.
Real estate valuation – Used for buying, selling, or securing a mortgage. This type of valuation assesses a property’s sale value, which is influenced by current market trends.
Insurance valuation – Used in insurance applications. It focuses on the cost of rebuilding or repairing a property based on current construction costs.
Insurance valuations are sometimes calculated using a $ per square metre estimate. However, general property valuers may not be qualified to quote rebuild costs. To ensure you’re not underinsured, it’s recommended to consult a surveyor for a more accurate figure.
It’s also important to remember that real estate and insurance valuations can differ significantly, sometimes in millions, and should not be used interchangeably.
How can property valuation impact insurance?
Insurers may use the property valuation report to determine what coverage is necessary and calculate the total cost of the premiums they’ll offer. A higher property value can mean more payouts are required in the event of a repair or replacement claim, leading to higher premiums. On the other hand, they may offer lower premiums to properties with lower value. The catch is this may mean less coverage and more out-of-pocket costs in case of a claim.
You need an accurate property valuation to balance adequate coverage and manageable premiums. This would help you avoid the following:
Over-insuring
Securing as much coverage as possible may sound like the safer option. However, insurers typically don’t pay more than the actual repair cost or the property’s market value. If your property is overvalued, this might lead to over-insuring and paying higher premiums for coverage you may not even need.
Underinsuring
Undervaluing your commercial property to pay lower premiums may sound like an easy way to save money, but it won’t help your business long-term. You may end up exposed to the risk of being underinsured in the event of a claim. Payouts from insurers may not cover enough repair or replacement costs, leading to additional financial strain.
Penalty fees
Policies may include a ‘co-insurance’ clause, which requires the property to be insured to a certain percentage of its value. If your property is found to have been undervalued, your insurance company may penalise you with a penalty fee or reduce the payout in the event of a claim.
Legal issues
An inaccurate commercial property valuation may also violate contractual agreements for leasing and mortgage.
It’s advisable to have your property professionally revalued every few years or whenever significant changes occur, such as renovations, expansions, or shifts in the local market. This helps you and your insurance provider update your coverage to match your business needs.
Having accurate and up-to-date valuation also minimises disputes during claims because insurers are better equipped to assess losses accurately, ensuring a smoother claims process.
Secure your commercial property
Having an accurate and up-to-date property valuation empowers you to make smart financial decisions while ensuring you have adequate insurance coverage to protect your investment. In business, preparation is everything—and staying ahead begins with understanding the true value of what you own.
Want to learn more about commercial property insurance? Connect with East West Insurance Brokers! Our team of expert insurance brokers can provide valuable insights into commercial property coverage for you and your business. Contact us today to get started!
FLEXIOriginally launched in the 1980s as a premium funding service helping clients pay insurance premiums in instalments, our platform has evolved to support brokers in offering flexible payment options.
Today, Flexigrow also provides business management software, enabling business owners to manage operations in one streamlined platform. CTA button:VISIT OUR WEBSITE