As a valued client of East West Insurance Brokers, you’re supported by a team of experts who bring more than just insurance knowledge to the table; they also have passions, hobbies, and aspirations that make them who they are. Get to know the people dedicated to looking after you and your business.
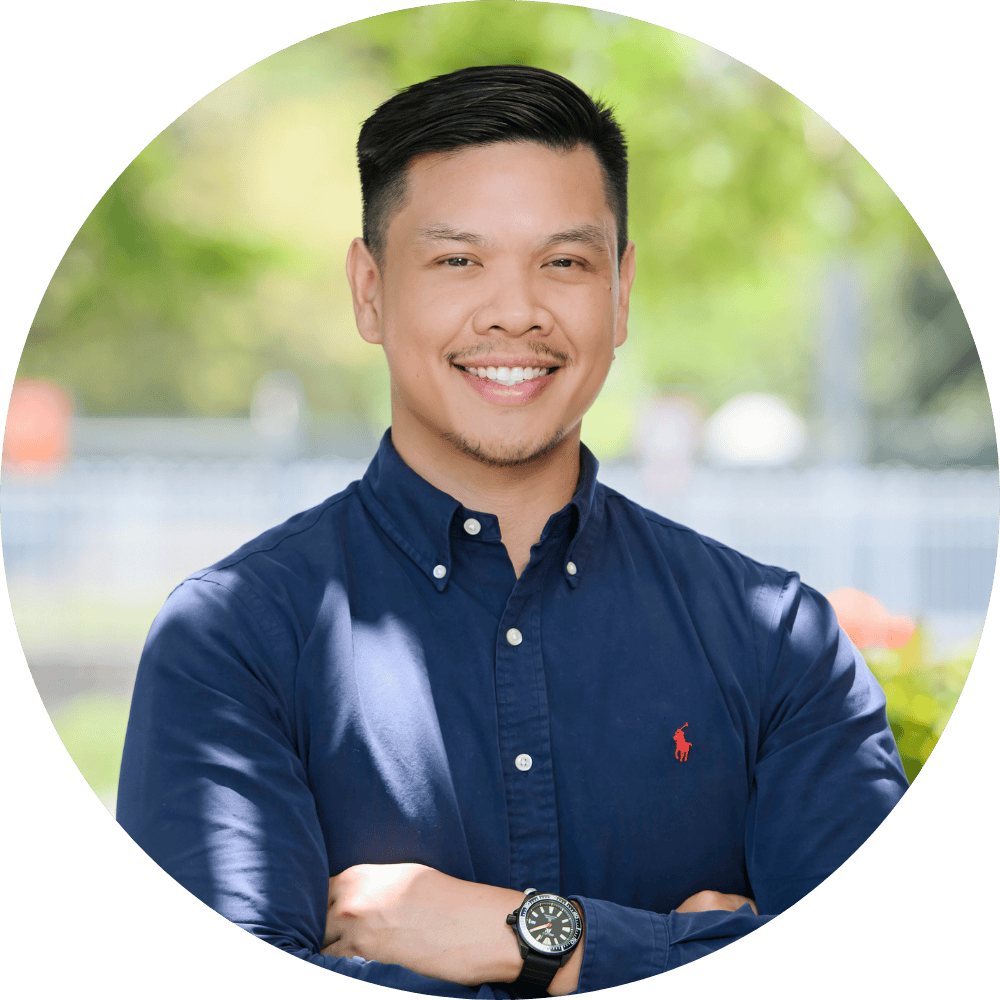
Christian Monzon Insurance Advisor
Christian works closely with clients and insurers, analysing renewals, managing client enquiries and helping find the right insurance solutions.
Outside of work, you’ll likely find him on the golf course, at the driving range or training for a half marathon. He’s always looking to improve his golf game and dreams of one day visiting Bora Bora.
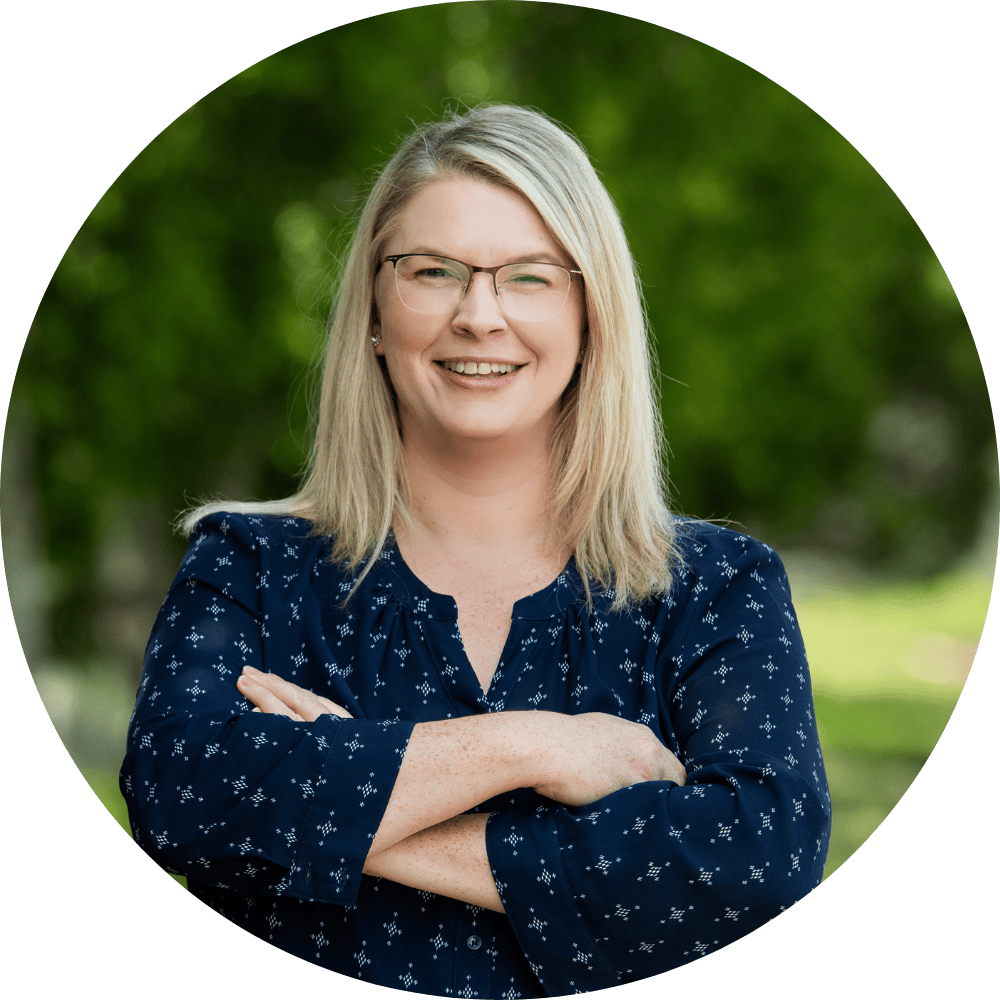
Rebecca Mulcahy Insurance Advisor
Rebecca works closely with clients to help them stay protected and works closely with colleagues to deliver great outcomes.
Outside of work, her weekends are all about family, with plenty of kids’ sporting events, birthday parties and playground adventures. In quieter moments, Rebecca enjoys jigsaw puzzles. She dreams of taking the family to Britain to explore their family history, culture and heritage.
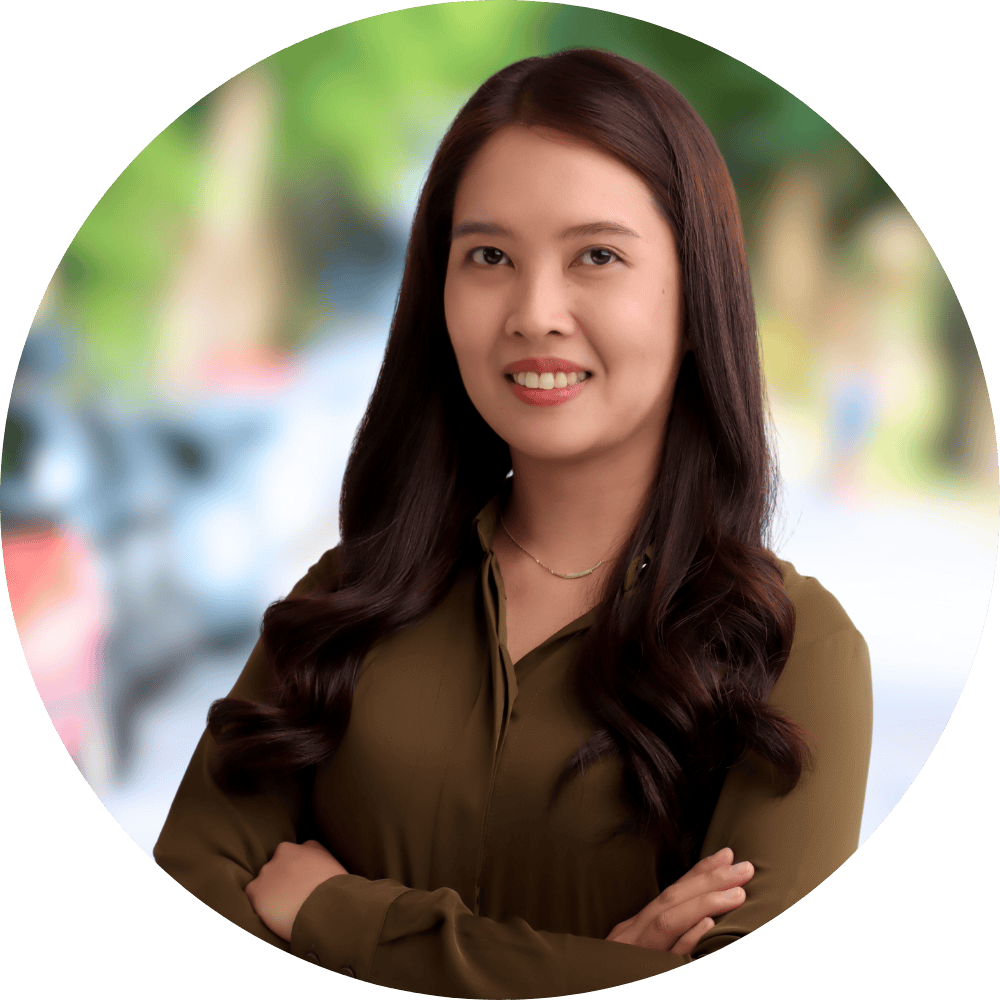
Zara Gomez Finance Manager
Zara oversees the financial planning, reporting and operational finance functions, helping to ensure the company’s ongoing financial success.
Outside of work, she enjoys DIY projects and planning overseas adventures, often organising every detail from itineraries to bookings. A road trip through Switzerland tops her travel bucket list, and she’s keen to sharpen her driving skills to make it happen.
As a valued client of East West Insurance Brokers, you’re supported by a team of experts who bring more than just insurance knowledge to the table; they also have passions, hobbies, and aspirations that make them who they are. Get to know the people dedicated to looking after you and your business.
Rebecca Sawers Chief Insurance Officer
Rebecca leads the group’s insurance divisions, focusing on strategy and growth, through the ever-changing industry.
Outside of work, you’ll often find her coaching her daughter’s netball team and helping young players develop their skills. She hopes to one day conquer a marathon and has Turkey and Italy’s Amalfi Coast at the top of her travel bucket list.
Michael Traill Insurance Advisor
Michael helps business owners find suitable insurance and manages small business insurance renewals.
Outside of work, he’s a self-confessed night owl who enjoys discovering new music, gaming, and exploring niche topics. He would love to learn Mandarin and dreams of visiting Antarctica one day, with China also high on his travel list.
Jose Flores Claims Assistant
Jose is passionate about guiding clients through the claims process from start to finish.
On weekends, he enjoys attending cosplay events, crafting costumes, gaming, and going on day trips. Jose also hopes to attend the 18th-century themed Fêtes Galantes ball at the Palace of Versailles, one of his top must-visit destinations.
As a valued client of East West Insurance Brokers, you’re supported by a team of experts who bring more than just insurance knowledge to the table; they also have passions, hobbies, and aspirations that make them who they are. Get to know the people dedicated to looking after you and your business.
Rawinia Lim Head of Claims
Rawinia manages complex claims, ensures smooth coordination with insurers, and handle escalations when needed.
Rawinia enjoys walking her dog and unwinding at home. She’s keen to explore pottery as a new hobby, and her travel wish list includes Greece, Thailand, and a return trip to Ireland.
Alicia Newell Executive Assistant
Alicia manages staff policies and supports Insurance Advisors to deliver exceptional services to our clients.
When not at work, you’ll find her at the gym or out enjoying meals, gardening, or taking her kelpie on adventures. She hopes to explore pottery and has Canada at the top of her travel list to see her favourite comedian and experience the wilderness
Shreya Sharma Marketing Manager
Shreya oversees the marketing team and leads all aspects of marketing for the business.
Outside of work, you’ll find her gardening, hiking, or experimenting with new recipes. She’s keen to explore creative pursuits like pottery or textured canvas art, with South Africa currently at the top of her travel wish list.
See what our team are loving this quarter
Jamie Olivers Gnarly Madras Lamb Traybake
Ingredients
2kg Lamb Shoulder (Bone In)
180g Madras Curry Paste
250g Yellow Split Peas
3 Red Onions
4 Tomatoes
1 Potato
6cm Ginger
1 bulb of Garlic
15g Coriander
12 Cloves
Method
1. Score the lamb and season with salt and pepper. 2. Rub with half the curry paste. 3. Place yellow split peas in a deep roasting tray with all the other ingredients along with the remaining curry paste. 4. Stir in 1.2L of boiling water and sit the lamb on top. 5. Tightly cover with tin foil and roast at 170 degrees for 4.5 hours. 6. Remove foil, baste with the tray juices.
When arranging insurance for a commercial property, many owners make a common mistake: using the purchase price as the sum insured.
On the surface, it feels logical. If that’s what you paid for the property, surely that’s what it’s worth? However, the purchase price doesn’t always reflect the actual cost of rebuilding.
Purchase Price vs. Rebuild Value
It’s important to understand the difference between the purchase price and rebuild value when it comes time to insuring your property. Yes, both relate to what your property is worth, but they represent and serve very different things.
Purchase Price
The purchase price of a property represents the total amount paid to acquire it on the market. It’s affected by several factors, which include:
The value of the land.
The property’s location and market demand.
Broader economic conditions at the time of purchase.
None of these is relevant to an insurer if your building is damaged or destroyed. Insurance is about replacing the structure itself, not the land it sits on.
Rebuild Value
The sum insured is generally expected to reflect the full replacement value of the building, which includes:
Demolition and debris removal.
Professional fees (engineers, architects, surveyors).
Current labour and material costs.
Compliance upgrades (to meet today’s building codes).
What’s the difference?
The key difference between purchase price and rebuild value lies in what each represents. The purchase price reflects the property’s market value, including the land, location, and broader economic factors, while the rebuild value focuses solely on the cost to reconstruct the building if it were damaged or destroyed. This includes demolition, debris removal, professional fees, materials, labour, and any upgrades needed to meet current building codes. In short, insurance covers the cost to rebuild, not the market price you paid.
The cost of getting it wrong
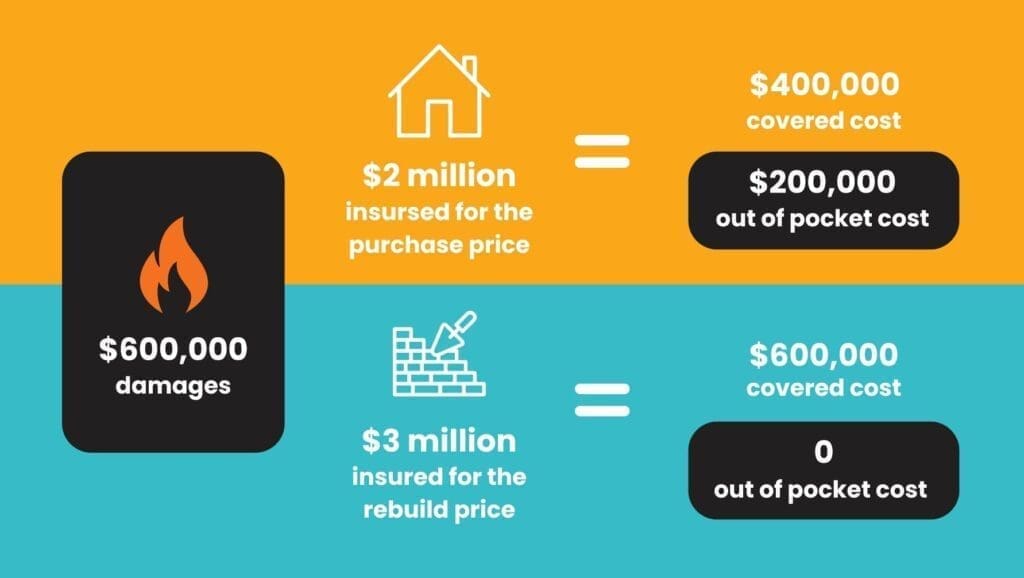
If your sum insured is based on the purchase price rather than a professional valuation, you risk being underinsured. And underinsurance doesn’t just affect you in the event of a total loss. It can also reduce your payout even in the case of a partial claim. For example:
A property was purchased for $2 million, but the actual rebuild cost is $3 million
The sum insured is set at $2 million (instead of $3 million).
A fire causes $600,000 worth of damage
Because the building was underinsured by one-third, the insurer may pay only two-thirds of the claim (about $400,000)
This could leave you, the owner, with $200,000 out of pocket expenses even though the damage wasn’t a total loss.
Why professional property valuations matter
Construction costs in Australia have surged in recent years, driven by shortages of materials and skilled labour. Without a proper valuation, it’s easy to underestimate the cost of rebuilding today compared to when you purchased the property. A professional building valuation gives you:
Confidence that your sums insured are accurate
Protection from co-insurance penalties
Peace of mind that your biggest asset is covered correctly
It’s best to arrange a professional building valuation every few years and review your insurance sums annually. That way, your cover keeps pace with any changes to your property, as well as rising rebuild costs and inflation.
Avoid underinsurance with proper valuation
The purchase price reflects market conditions, not rebuilding costs. Having a commercial property is already a significant investment, and underinsurance can create unexpected financial strain during claims. To safeguard your investment, arrange a professional building valuation and review it regularly. That way, your insurance truly reflects today’s replacement costs, not yesterday’s market value.
When it comes to protecting your assets and ensuring the sums are properly accounted for, a Broker would be a huge help. If you want advice or are interested in learning about available options for commercial property coverage, reach out to East West Insurance Brokers today.
FLEXIOriginally launched in the 1980s as a premium funding service helping clients pay insurance premiums in instalments, our platform has evolved to support brokers in offering flexible payment options.
Today, Flexigrow also provides business management software, enabling business owners to manage operations in one streamlined platform. CTA button:VISIT OUR WEBSITE