As a valued client of East West Insurance Brokers, you’re supported by a team of experts who bring more than just insurance knowledge to the table; they also have passions, hobbies, and aspirations that make them who they are. Get to know the people dedicated to looking after you and your business.
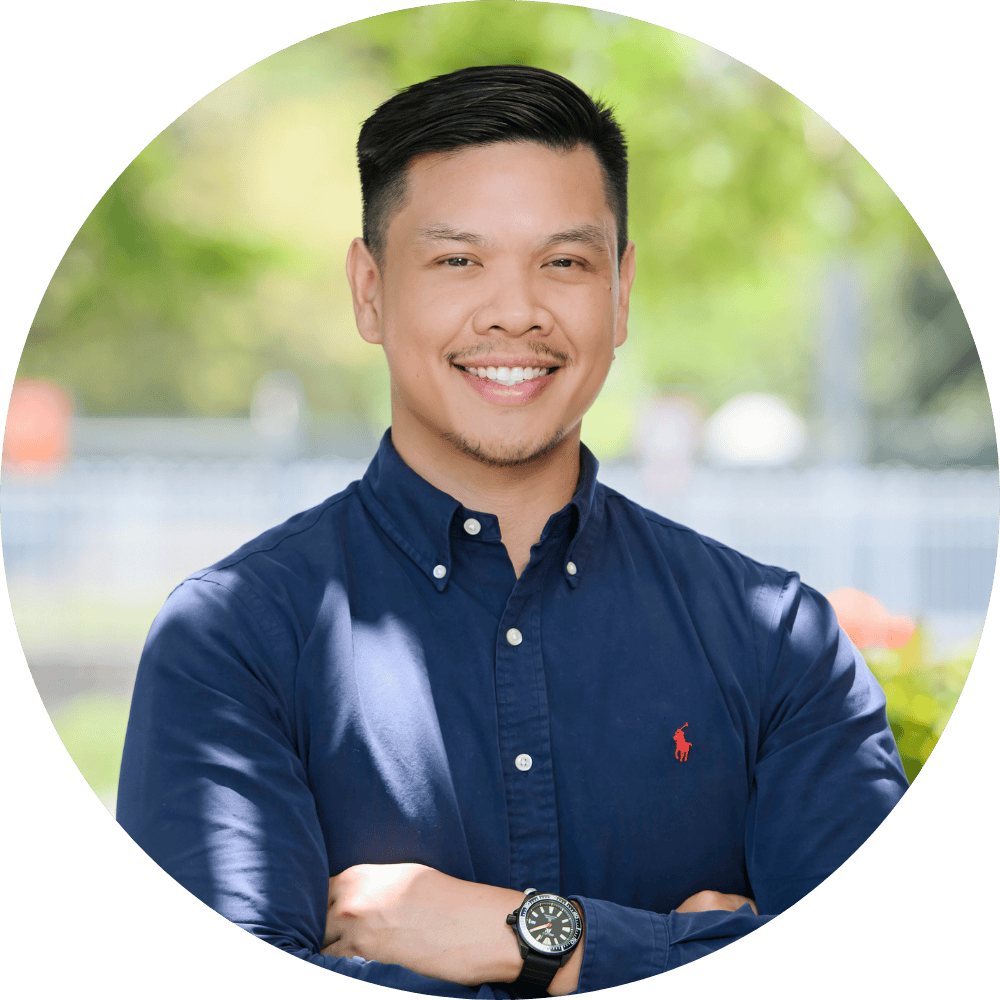
Christian Monzon Insurance Advisor
Christian works closely with clients and insurers, analysing renewals, managing client enquiries and helping find the right insurance solutions.
Outside of work, you’ll likely find him on the golf course, at the driving range or training for a half marathon. He’s always looking to improve his golf game and dreams of one day visiting Bora Bora.
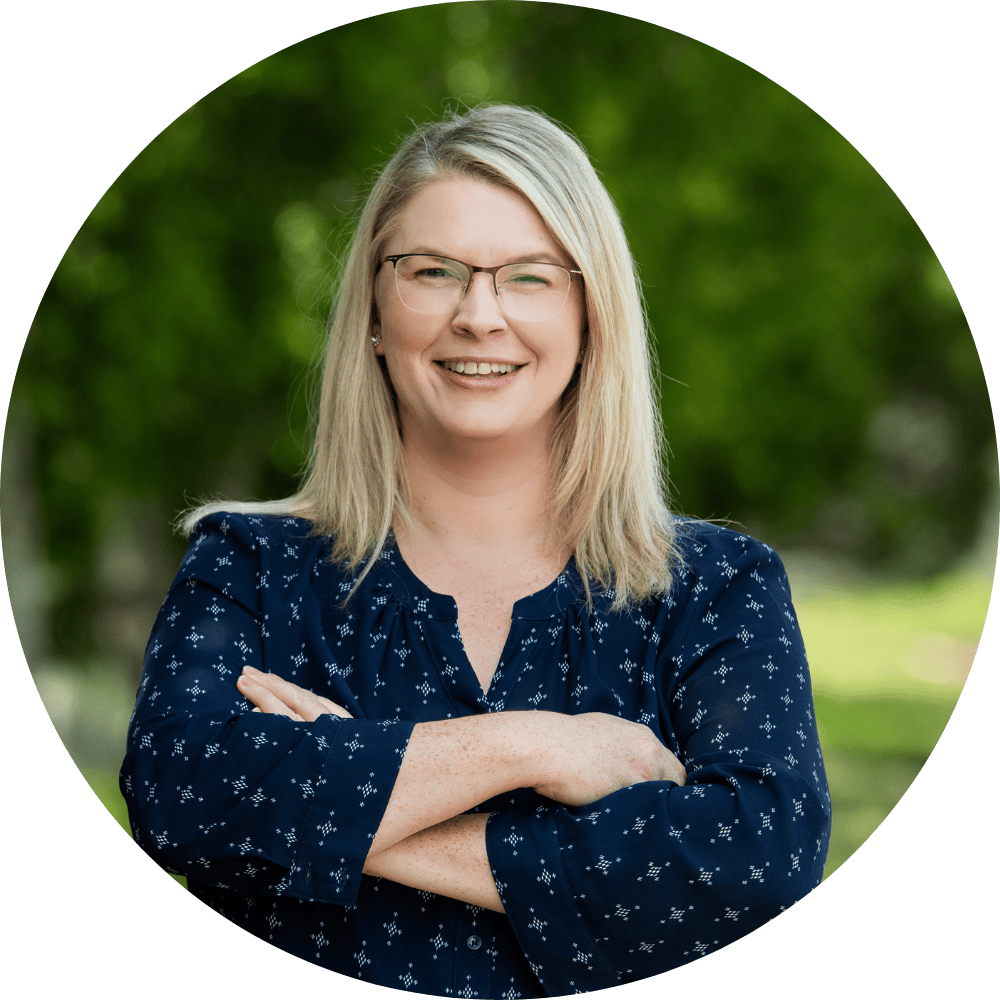
Rebecca Mulcahy Insurance Advisor
Rebecca works closely with clients to help them stay protected and works closely with colleagues to deliver great outcomes.
Outside of work, her weekends are all about family, with plenty of kids’ sporting events, birthday parties and playground adventures. In quieter moments, Rebecca enjoys jigsaw puzzles. She dreams of taking the family to Britain to explore their family history, culture and heritage.
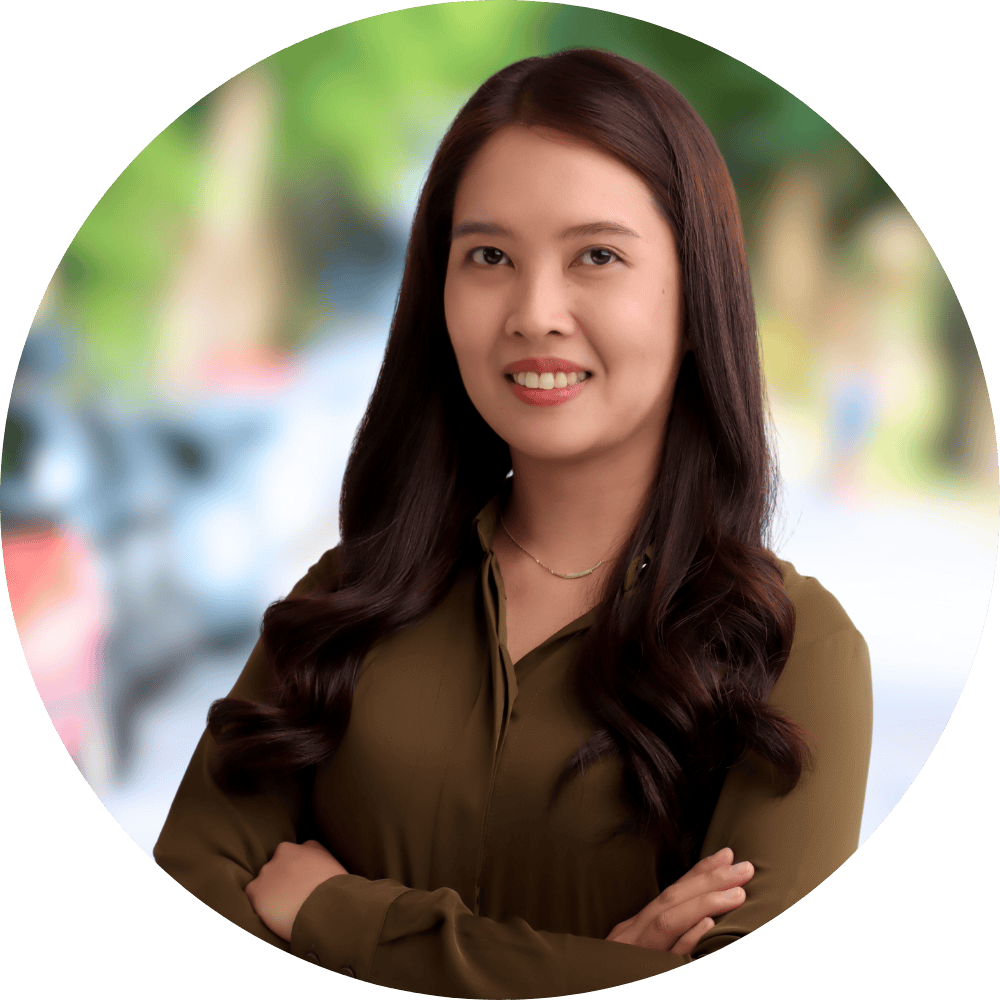
Zara Gomez Finance Manager
Zara oversees the financial planning, reporting and operational finance functions, helping to ensure the company’s ongoing financial success.
Outside of work, she enjoys DIY projects and planning overseas adventures, often organising every detail from itineraries to bookings. A road trip through Switzerland tops her travel bucket list, and she’s keen to sharpen her driving skills to make it happen.
If your business insurance renews in June, you may already know it can be a busy time for the insurance industry.
Many businesses choose June renewals because they align with the end of the financial year. However, this also means insurers are reviewing a high number of policies at the same time.
Moving your renewal away from this busy period may have some benefits, including:
1. More time for Insurers to assess your business
A quieter renewal period may give insurers more time to understand your business, assess your risks and consider the terms they can offer.
This can be especially helpful if your business has changed, your risks are more complex or your policy needs a more detailed review.
2. More opportunity for us to negotiate
Having more time can also give us greater opportunity to speak with underwriters, explore alternative markets and negotiate premiums and policy conditions on your behalf.
It allows us to thoroughly consider the options available and work with insurers to find the right solution for your business.
You May Be Able to Change Your Renewal Date
Many business owners with a June renewal assume they need to renew in June every year. In some cases, that’s not necessarily the case.
Depending on your insurer and policy, we may be able to arrange a one-off policy term of 8 to 16 months.
This could move your next renewal to a different time of year.
For example, if your policy currently renews in June, we may be able to extend the policy term so your next renewal falls later in the year, outside the industry’s peak renewal period.
Is It Worth Asking?
Changing your renewal date won’t suit every business.
We’ll look at your circumstances, see whether it’s an option and explain what may work best for you.
Planning ahead could give insurers more time to assess your business and give us more opportunity to negotiate the right cover and terms on your behalf.
We know when something goes wrong, making an insurance claim can feel like one extra hassle.
As a business owner we also know your priority is usually getting things back to normal or continuing to run with as little disruption as possible.
However, what you do after an incident can affect how smoothly your claim is handled.
As your insurance advisor, we are here to help guide you through the claims process. Here are five of the most common mistakes that can make a claim more difficult.
1. Waiting too long to notify us
One of the most common mistakes we see is waiting too long to report an incident.
You may think the damage is minor or you want to look into all details of what happened before contacting us.
However, it is best to let us know as soon as possible.
Early notification gives us the chance to understand what has happened and help you take the right steps.
Your policy may also have rules about when and how you need to report a claim.
Our advice: If something happens that could lead to a claim, contact us as soon as possible. Even if you are unsure whether you want to make a claim, we can help you understand your options.
2. Not keeping evidence
Good records can make a big difference during a claim.
Where it is safe to do so, take photos and videos of the damage. Keep receipts, invoices, repair quotes and other records linked to the incident.
It is also useful to keep emails and other messages about the incident. This may include conversations with contractors, suppliers or other people involved.
The more information we have, the easier it can be to understand what happened and assess the loss.
Our advice: Keep records of the incident, the damage and any costs. Don’t rely on memory alone.
3. Starting repairs too soon
We understand that when your business is damaged, you want to fix the problem straight away.
In some cases, urgent action is needed to make the area safe or stop the damage from getting worse.
However, starting non-urgent repairs before speaking with us may make it harder to assess the damage. The insurer may need to inspect the property or arrange an assessment before repairs begin.
Our advice: Contact us before starting non-urgent repairs. If urgent work is needed, take photos first where it is safe to do so and keep records of the work and costs.
4. Assuming something is covered
It is easy to think that if you have insurance, your loss must be covered.
But insurance policies can be complex. They can include different terms, conditions, exclusions, limits and excesses.
Cover can also depend on what happened and how the loss occurred.
Rather than making assumptions, talk to us about your policy and the situation. We can help explain what your cover may respond to and what steps you should take next.
Our advice: Don’t guess. If you are unsure whether something is covered, ask us before making decisions.
5. Not understanding your excess
Your excess is the amount you may need to pay towards a claim.
The amount can vary depending on your policy and the type of claim. Some policies may also have different excesses for certain events.
Knowing your excess before you need to make a claim can help you understand the possible cost to your business.
Our advice: Make sure you know what excesses apply to your policies. If you are unsure, we’re happy to explain them.
What should you do if something goes wrong?
EvEvery claim is different, but there are some simple steps you can take.
Make the area safe. Put the safety of your employees, customers and others first.
Prevent further damage. Take reasonable steps to protect your property where it is safe to do so.
Document the incident. Take photos and videos and write down what happened.
Contact us. Let your broker know as soon as possible.
Keep your records. Save invoices, receipts, quotes and other documents.
Importantly we are here to help, ask questions. If you are unsure what to do, speak with us before taking action.
The best time to review your insurance is before a claim
A claim can highlight whether your insurance still matches your business needs.
Your business may have changed since your policy was first arranged. You may have bought new equipment, increased your stock, moved premises, hired more employees or changed how you operate.
That’s why regular insurance reviews are important.
At East West Insurance Brokers, we work with you to understand your business and help you make informed decisions about your insurance.
If your business has changed, speak with your broker. We can review your cover and help make sure it still suits your needs.
Because the best time to find a gap in your insurance is before you need to make a claim.
Most business owners think Business Interruption insurance only covers damage to their own premises.
But when we review a client’s cover, we look at more than their own business.
We also consider the businesses they rely on, such as suppliers, customers and storage providers.
If one of these businesses is affected, it could also disrupt your business and reduce your income.
This is where Contingent Business Interruption cover can help.
How Can Contingent Business Interruption Cover Help?
Your business does not need to be directly damaged to suffer a loss.
If a business you rely on is affected, it could cause delays, lower sales or lost income.
When we review Business Interruption cover with our clients, these are some of the key areas we encourage them to think about.
1.Your Suppliers or Manufacturers
Many businesses rely on suppliers for products, materials or equipment.
But what would happen if one of your key suppliers could no longer deliver?
If their premises are damaged, it could delay your business and affect your income.
For example:
A dressmaker cannot source fabric after a supplier’s warehouse is damaged by fire.
A café cannot receive deliveries after a bakery supplier is damaged by a storm.
A construction company faces delays after a supplier’s factory is damaged by fire.
Depending on your policy, Contingent Business Interruption insurance may help cover the financial impact.
This is something we recommend considering if your business relies heavily on a small number of suppliers.
2. Your Customers
Sometimes, the disruption can come from the other side of your business; your customers.
If a major customer is affected by an insured event, they may not be able to operate as normal. They may reduce or stop buying your products or services.
For example, imagine you supply products to a restaurant that is damaged by a storm and needs to close for repairs.
While the restaurant is closed, they may not be able to purchase from you. If they are a major customer, this could have a real impact on your income.
If your business relies on a small number of key customers, Contingent Business Interruption cover may help protect your income.
3.Third-Party Storage Facilities
We also see businesses storing stock at warehouses or storage facilities they do not own.
If that location is damaged, it could delay orders and affect your ability to trade.
Your policy may provide protection if the storage facility belongs to another business.
However, we also recommend checking that any stock stored at third-party locations is properly insured.
Two Important Things to Know
Contingent Business Interruption cover can provide valuable protection, but there are some important limits to understand.
1. The Damage Must Be Covered
For your claim to be covered, the damage will usually need to be something your Property Damage insurance would cover.
For example, your supplier’s warehouse is damaged by flood, but your Property Damage policy does not include flood cover.
In this situation, your Business Interruption claim may not be covered.
This is why we always encourage our clients to look at their Property Damage and Business Interruption insurance together. The two covers can work closely together when a claim occurs.
2.Your Claim May Be Limited to 20%
Many insurers place limits on claims involving suppliers, customers or storage facilities that are not specifically listed on your policy.
A common limit is 20% of your Business Interruption Sum Insured, although this can vary between insurers and policies.
For example, if your Business Interruption Sum Insured is $500,000, your claim for an unnamed supplier, customer or storage facility may be limited to $100,000.
For a business that relies heavily on one key supplier or customer, that limit may not be enough.
When we review your policy, we can help you understand these limits and whether they provide enough protection for your business.
Is Your Insurance Keeping Up With Your Business?
Your business does not stay the same forever.
You may work with new suppliers, gain bigger customers, hold more stock or change the way you operate.
That is why we recommend reviewing your insurance regularly.
We encourage you to ask yourself:
What would happen if my main supplier stopped operating?
What if my biggest customer could no longer trade?
Could my business continue if my stock was damaged at another location?
How long could I continue operating if a key business partner was affected?
If the answers raise some concerns, it may be time to review your cover.
As your broker, we can help you understand your policy, explain any limits and look at whether your current cover still meets your needs.
A quick conversation with us today could help you identify a gap before you need to make a claim.
FLEXIOriginally launched in the 1980s as a premium funding service helping clients pay insurance premiums in instalments, our platform has evolved to support brokers in offering flexible payment options.
Today, Flexigrow also provides business management software, enabling business owners to manage operations in one streamlined platform. CTA button:VISIT OUR WEBSITE